GUIDE: What is blockchain?
Blockchain, or block chain, is the technology that makes Bitcoin and thousands of cryptocurrencies possible. It sounds complicated, but the idea is simpler than it seems: it's a shared ledger that no one can secretly manipulate.
The basic idea: a shared ledger
Imagine a notebook where every payment made within a group of people is recorded. In the traditional system, a bank keeps that notebook: it decides what gets recorded, and you trust it to do so correctly. In a blockchain, the notebook is copied onto thousands of computers distributed around the world, and all of them have exactly the same version.
When someone sends a transaction, it's broadcast across the network. Computers verify that the payer has sufficient balance and that the digital signature is valid. If everything checks out, the transaction is grouped with others into a «block».
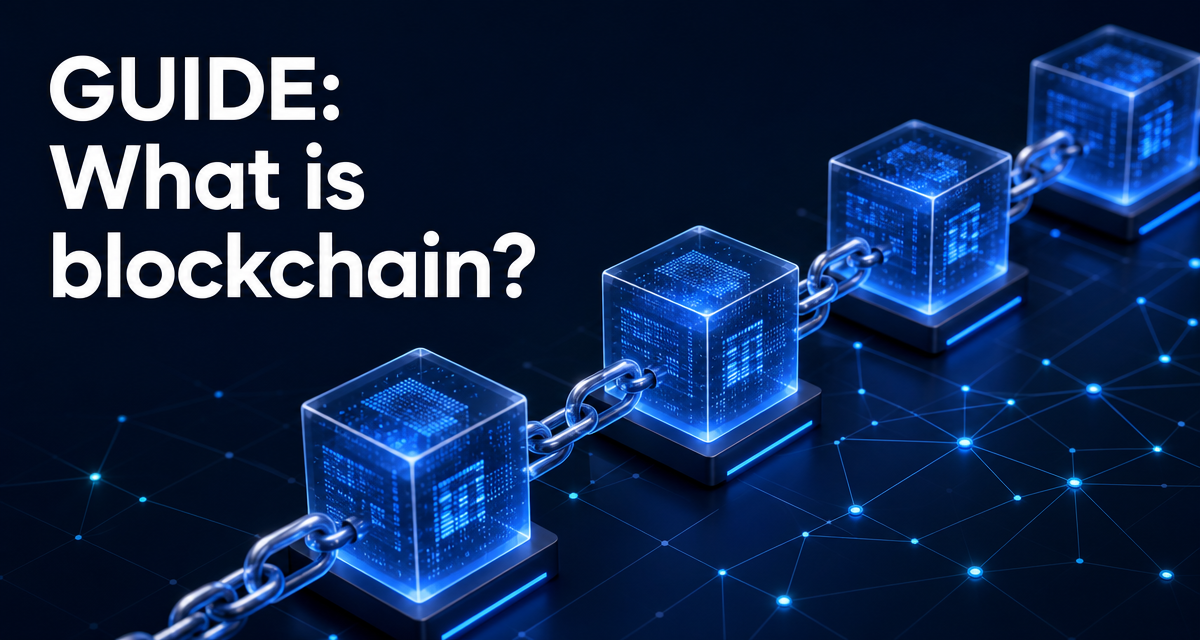
Each block is linked to the previous one by a cryptographic fingerprint called a hash. This fingerprint depends on the content of the block: if someone were to change even a single comma in an old transaction, the hash would change, and all subsequent blocks would no longer fit. That's why it's called a chain: the blocks are stitched together.
Why it's difficult to manipulate
To alter the history, it's not enough to edit a copy of the ledger; all subsequent blocks would have to be re-created, and the majority of the network convinced to accept that fraudulent version. In large networks like Bitcoin, this would require colossal computing power and an astronomical energy cost, far exceeding the benefit of the attack.
Added to this is transparency: anyone can download the full chain and verify it. There's no need to trust an authority; simply check the math. It's a paradigm shift: from 'trust the intermediary' to 'verify yourself'.
The flip side is that blockchain is slow and expensive compared to a private database. That's why not every application needs blockchain: it only makes sense when multiple parties who don't trust each other need to share a common record.
How thousands of computers agree
The mechanism participants use to agree on the valid version is called consensus. Bitcoin uses proof of work: miners compete by solving a mathematical problem, and whoever solves it proposes the next block and receives a reward.
Other networks, like Ethereum, use proof of stake: validators lock up their own coins as collateral and lose part of them if they try to cheat. It consumes much less energy, although it tends to concentrate power in those with more capital.
In both cases, the goal is the same: to make lying more expensive than behaving honestly.
Uses beyond cryptocurrencies
The same technology can be used to record things that aren't money. It's used to trace supply chains (to know which farm a coffee comes from), to certify academic qualifications, to tokenize bonds and funds, or to create smart contracts: programs that execute themselves when certain conditions are met, without the need for an intermediary to enforce them.
It's important to be realistic: many projects advertised as blockchain would work just as well with a regular database. The useful question is always the same: are there multiple independent parties that need a common record without trusting each other? If the answer is no, blockchain is probably unnecessary.
Limits, myths, and how to evaluate a blockchain project
Once the basic idea is understood, the next step is to learn to distinguish what a blockchain does well from what is merely attributed to it in marketing. The technology solves a very specific problem: allowing multiple parties who don't trust each other to share the same ledger without relying on an intermediary. Everything else—speed, cost, privacy, ease of use—is usually worse than in a traditional database. A public blockchain repeats the same work across thousands of nodes, and that redundancy is precisely what makes it resilient, but also slow and expensive compared to a central server.
This leads to three limits that should be clear. The first is scalability: the Bitcoin network processes a few transactions per second, far behind a card network. This is why higher layers exist, such as Lightning Network, which bundle many off-chain payments and only settle the final result on-chain. The second is privacy: contrary to what many people believe, a public blockchain is not anonymous, but pseudonymous. Every movement is recorded forever, and if an address is associated with your identity on an exchange, its entire history becomes exposed. The third is irreversibility: there is no customer service that can undo a transfer sent to the wrong address.
There are also myths that need debunking. Just because something is on a blockchain doesn't mean it's true: the chain guarantees that data hasn't been altered since it was recorded, but not that it was correct when written. If someone certifies a diamond as authentic and lies, the lie will be immutably recorded. Nor is it true that every blockchain is decentralized: many enterprise networks are controlled by a handful of known participants, which practically turns them into shared databases with additional steps.
To evaluate a project without technical knowledge, ask yourself four questions. Who validates the transactions, and how many independent participants are there? What happens if the founding team disappears tomorrow; does the network continue to function? Is the code open-source and auditable by third parties? And what real problem does it solve that wouldn't be solved just as well with a conventional database? If a project cannot clearly answer these four questions, prudence suggests staying away. Applying this basic filter helps avoid most empty projects and focuses on networks with a track record, community, and demonstrable use.
If you want to understand how all this applies to the most well-known currency, continue with our guide on what Bitcoin is and how it works.
Learn more about Bitcoin